Your income is your largest asset. Protect it properly.
Specialized disability coverage for physicians, dentists, lawyers and pharmacists. Own-occupation protection built around your specialty, not a generic job description.
In 20 minutes you will have two numbers: what your policy would actually pay, and what your income actually needs.
Let’s protect your income, properly.
Prefer to pick a time? See my calendar
Your coverage is only as good as one sentence in it
Group and association plans are a reasonable floor. They cap benefits at a fixed monthly maximum set for the average member, not for a specialist billing several times that. The wording that decides your claim is the wording almost nobody reads in advance.
See what your policy would not payFour questions most professionals cannot answer about their own policy
If you can answer all four without checking, you are in better shape than most of the people I speak to. If you cannot, that is usually exactly where the gap turns out to be.
01
Would your policy still pay you if you could teach?
A dentist who loses fine motor control in one hand can often still lecture, consult or supervise. Under an any-occupation definition, that can be enough for benefits to stop. Under true own-occupation wording, it is not. One sentence in your contract decides which applies to you, and most professionals have never read it.
02
What percentage of your income would actually be replaced?
Group and association plans are usually built around an average member, not a specialist billing several times that. The shortfall rarely surfaces until a claim is filed, and by that point the number is already fixed. Working out your real figure takes about ten minutes.
03
Who pays your staff while you recover?
Rent, salaries and equipment leases do not pause because you are in a hospital bed. Practice owners often discover that their personal benefit is quietly funding payroll instead of their household. There is a separate policy designed so that does not happen.
04
Will you still be insurable at the income you earn in five years?
Coverage is priced on the health you have today. One diagnosis between now and then can close the door on increasing it later, at exactly the point your income is highest. A future insurability option holds that door open without further medical underwriting.
Coverage, definitions and eligibility vary by insurer and by occupation, and depend on your health, income and practice structure. Policy wording governs in all cases. The information on this page is general in nature and is not financial, tax or legal advice. The first step is a conversation to see what applies to you.
Twenty minutes now, or a surprise at claim time.
Send me your specialty and what you currently hold, and I will tell you plainly where the gaps are. If there are none, I will tell you that too. You can give me a call or message me on WhatsApp.
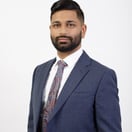
Sumreet Dhaliwal, LLQP
Advice here is personal by design. I am licensed across Canada and independent among the major Canadian insurers, so the wording in your contract is compared across the market rather than within a single carrier's shelf. If the coverage you already hold is sound, I am candid about that too.