Protection designed around the life you’ve built.
Most people find out their coverage no longer fits their life at the worst possible moment. 20 minutes is usually enough to know where you stand.
Whether you already have coverage or are starting from scratch, start with a conversation. Nothing is decided in it.
Let’s find the right coverage, together.
Prefer to pick a time? See my calendar
Start with the situation, not the product
The coverage you bought is not the coverage you need now
Most policies are bought once and never looked at again. Salaries rise, mortgages change, children arrive, businesses incorporate. The policy stays exactly as it was. A review costs nothing and usually takes 20 minutes.
See where your coverage standsWhole life
Permanent coverage that builds guaranteed cash value you can actually access. The part most people miss is that it stops being a premium and becomes an asset.
Read more
Coverage that lasts your whole life, with a guaranteed cash value that grows every year. Once that value builds you can borrow against it for a business opportunity, a shortfall, or retirement income, without cancelling the policy.
It costs more than term for the same death benefit, so it earns its place when you want the asset as well as the protection. Most often used by incorporated owners and people who have already filled their registered accounts.
Term life
The most coverage for the least cost, sized to the years that actually carry risk: the mortgage, the children at home, the business loan.
Read more
The most coverage for the least money, for a fixed period, usually ten, twenty or thirty years. If you die during the term it pays out. If you outlive it, it simply ends.
It suits the years that carry the most risk: the mortgage, the children at home, the business loan. Most term policies can be converted to permanent coverage later without a new medical, which matters a great deal if your health changes.
Universal life
Permanent coverage with investment choice, for people who would rather have control over how the growth is handled than be handed a default.
Read more
Permanent coverage where the growth is separated from the insurance, so you choose how the cash value is invested rather than accepting a default.
That flexibility runs both ways. The returns are not guaranteed the way whole life's are, and the policy needs reviewing rather than filing away. It suits people who are comfortable making investment decisions.
Disability
Your income pays for everything else you own. Most people insure the house and the car long before they insure the thing that pays for both.
Read more
Replaces part of your income if illness or injury stops you working. Your income pays for everything else you own, and it is the asset most people never insure.
The wording matters more than the price. A policy that pays only if you cannot work at any job is a very different product from one that pays if you cannot work in your own occupation.
Critical illness
A lump sum on diagnosis, to use however you need it. Some versions refund every premium you paid if you never claim, which surprises most people.
Read more
Pays a lump sum on diagnosis of a covered condition, most commonly cancer, heart attack or stroke. You decide what it is for: treatment not covered publicly, time away from work, or keeping the business running.
Some versions return every premium you paid if you never claim, which makes the decision easier for people who dislike paying for something they may never use.
Not sure where to start?
Almost nobody arrives knowing which product they need. Start with the situation instead, and the answer usually becomes obvious.
See my calendar →Where owners most often leave money on the table
Four planning conversations that come up again and again with incorporated clients. Most owners have never been walked through a single one of them.
01
Premiums that do not sit idle
There is a structure where the corporation funds a permanent policy and then borrows against its accumulating value, so the same dollars stand behind both the coverage and the business. It hinges on lending terms and your balance sheet, which is exactly why it is worth checking rather than assuming it is out of reach.
02
The account most shareholders have never heard of
A corporation that receives a life insurance benefit can often credit much of it to a notional account that allows the money to reach shareholders without tax. Few owners know it exists until somebody maps it out on paper for them.
03
Locking in today’s value before it grows
Freezing share value pins the eventual tax exposure to today’s number and lets future growth accrue to the next generation. Insurance is what settles the bill when it finally arrives, so the company itself does not have to be sold to pay it.
04
The agreement nobody funds until it is too late
Plenty of shareholder agreements spell out what happens when an owner dies. Far fewer say where the money is supposed to come from. Funding it means the surviving owner can act on the agreement rather than renegotiate it with a grieving family.
These strategies depend on your corporate structure and personal situation, and involve tax and legal considerations. Tax treatment is subject to change. They are implemented together with your accountant and lawyer, and nothing here is financial, tax or legal advice. The first step is a conversation to see what applies to you.
Simple, transparent, unhurried
A conversation, not a pitch
A 20-minute call to understand your situation, covering family, business, income and goals. You will leave with clarity even if we never speak again.
A plan in plain language
Options are compared across insurers, side by side. You will see what each costs, what it does, and what I would choose in your position, with the reasoning.
Reviewed as life changes
Coverage is revisited at every milestone, from a new home or child to incorporation or the sale of a business, so it always fits.
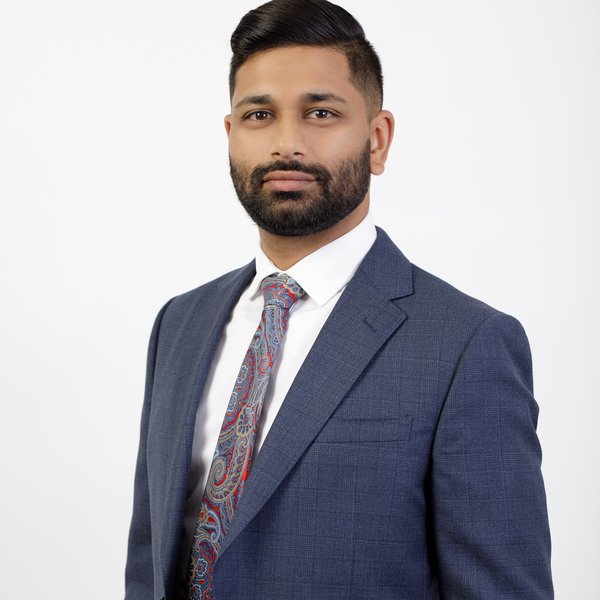
Advice you can actually understand
I am Sumreet Dhaliwal, an advisor licensed across Canada, helping people grow their financial literacy and protect what they have worked for. Insurance is full of jargon and pressure. My job is to remove both, so you can make a confident decision on your own terms.
The first conversation costs nothing.
Tell me a little about your situation and I will tell you plainly where the gaps are. If there are none, I will tell you that too. You can give me a call or message me on WhatsApp.